
Key Takeaways
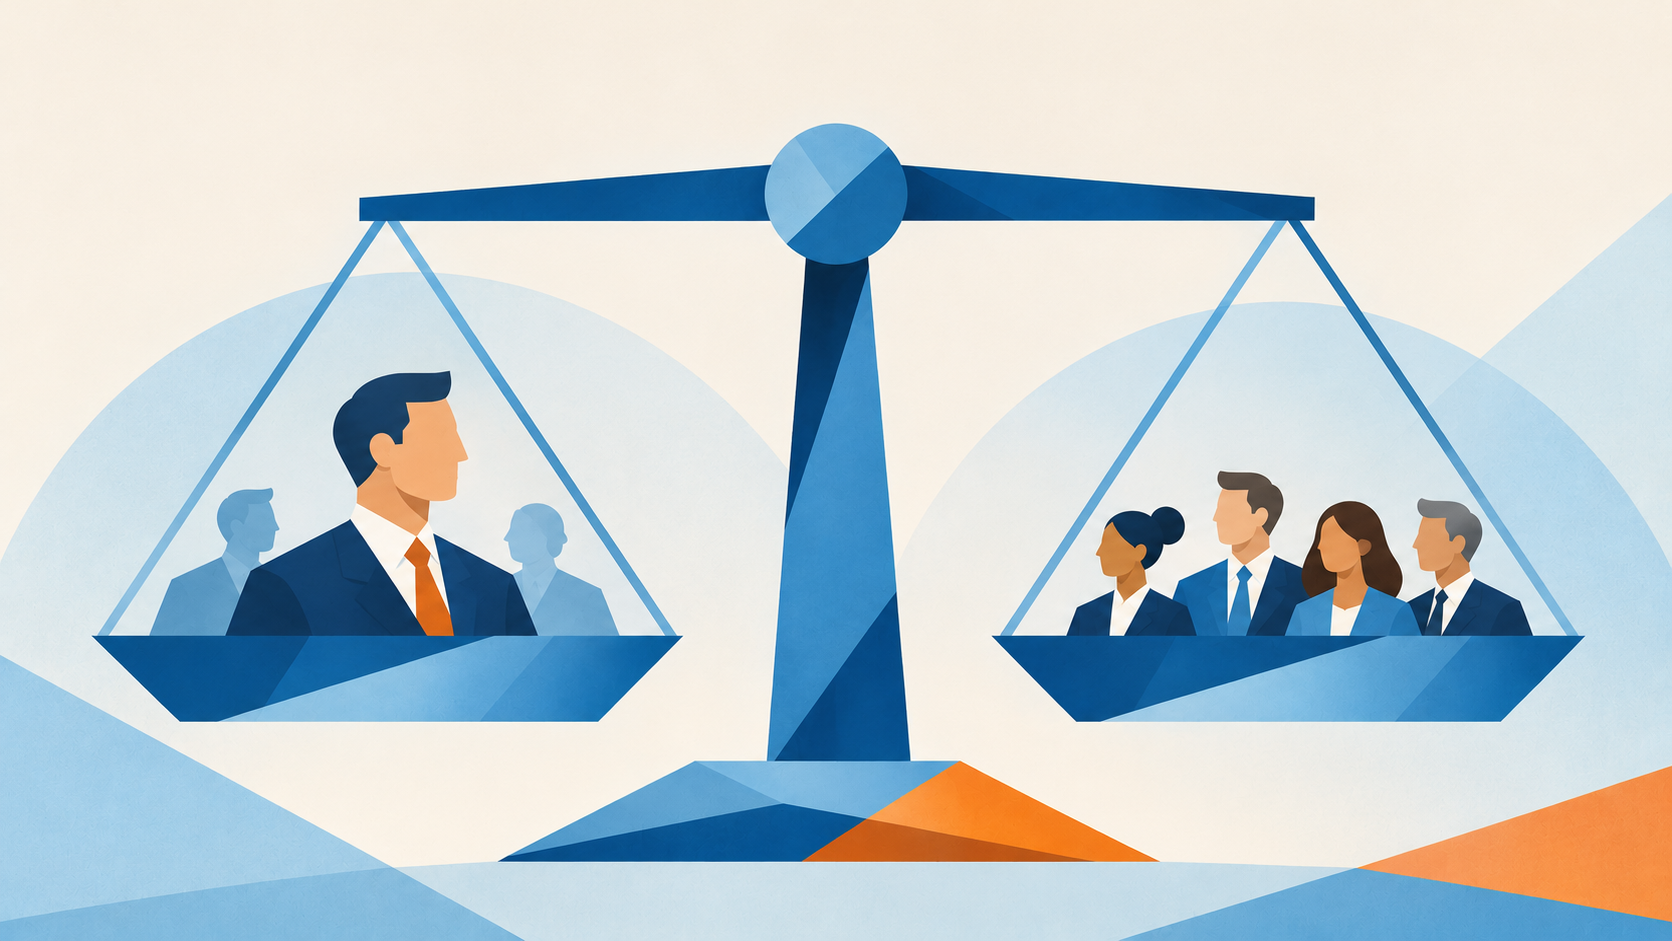
For decades, corporate governance has rested on a seemingly straightforward principle: economic ownership and voting power should travel together.
One share, one vote is intuitively attractive. It gives shareholders a mechanism to hold boards and management accountable, supports an effective market for corporate control and limits the ability of insiders to entrench themselves while bearing only a fraction of the economic consequences of their decisions.
Yet some of today’s most innovative companies pose a difficult question for investors: how should they weigh opportunity against influence?
Should investors pass on a company, including at IPO, because its founder retains voting control? Or can accepting a limited say in governance be a reasonable tradeoff for giving an exceptional entrepreneur the freedom to execute a long-term vision?
I believe the answer lies somewhere between governance orthodoxy and founder exceptionalism.
Structure Matters, but so Does Practice
There are two broad ways to think about governance.
The first emphasizes structure: independent boards, separation of committee authority and voting rights proportional to economic ownership. This approach has considerable merit. Good governance systems are deliberately designed for circumstances in which individuals eventually disappoint us.
But governance can also be judged by how it is practiced.
An independent board does not guarantee a well-run company. Equally, a company with an unconventional governance structure can allocate capital wisely, hold management to account and safeguard minority shareholders’ interests.
That distinction becomes particularly important with founder-led companies.
Some entrepreneurs create enormous value, precisely because they are prepared to pursue strategies that conventional public markets might reject. Long-term investments can look irrational through the lens of quarterly earnings. Designing products for markets that do not yet exist and that cannot be validated can appear irrational right up until they define a category no one else saw coming.
A governance system designed primarily to constrain management can therefore create its own cost: it may constrain the very people investors are relying upon to create value.
Investors Are Not Buying Governance in Isolation
At an IPO, investors purchase a bundle of economic rights, governance rights and expected future cash flows. Voting power is an important component of that bundle, but it isn't the investment itself.
If a company clearly states that its founder will retain voting control, investors can incorporate that limitation into their assessment of value.
That doesn't make unequal voting rights desirable. It changes the question.
Investors routinely accept additional credit, liquidity, concentration or duration risk when they believe the prospective return compensates them. Governance risk shouldn't be any different. The question should be whether the expected benefits of concentrated control justify the governance risk shareholders are accepting.
Companies such as Meta and Alphabet make this debate particularly interesting. They combine substantial founder influence with businesses that have created tremendous economic value. Their success does not prove that unequal voting rights create superior outcomes. But it should make us cautious about assuming that formal governance best practices are a requirement for such outcomes.
The Real Issue Is Permanence
For me, the case becomes more difficult as the time horizon extends.
The founder who justifies disproportionate voting power at an IPO may not be at the helm 20 years later, and if they are, they may not be the same leader they were at the time of founding.
Minority shareholders may continue supplying most of the economic capital while having permanently limited their ability to influence the company’s governance. Concentrated voting rights can also weaken an important disciplinary mechanism in public markets: the market for corporate control.
This exposes the fundamental weakness in permanent dual-class structures.
An exceptional founder may justify exceptional treatment. That does not mean an exceptional governance structure should carry on indefinitely.
Even a visionary founder can lose focus, become less receptive to challenge or eventually be replaced by a less capable successor. A structure designed to preserve long-term entrepreneurial judgment can, over time, become a means of entrenching control. Governance needs to contemplate both circumstances.
Competition for IPOs Complicates the Picture
There is another uncomfortable reality: stock exchanges compete for listings.
The UK, for example, liberalized its approach to dual-class structures as part of broader 2024 listing-rule reforms intended to make London more competitive.1
That creates the possibility of a governance version of regulatory competition.
A highly sought-after technology company considering several listing options has substantial negotiating leverage. Similarly, in an oversubscribed IPO, the argument that investors can simply reject unacceptable governance provisions is theoretically correct but practically more complicated.
Fear of missing out isn't a governance principle. But it is an investment reality. Especially when the concentration in major indices to a few select founder-led stocks results in significant tracking risk for those who opt out.
The danger is that accommodations originally intended for genuinely exceptional circumstances gradually become standard practice.
Sunset Provisions Offer a Better Compromise
This is why I find sunset provisions considerably more compelling than either extreme in this debate.
Investors don't necessarily need to choose between one-share-one-vote structures from the first day of public ownership and disproportionate founder control forever.
Enhanced voting rights could expire after a specified period, when the founder ceases to serve in an executive capacity, when the founder's economic ownership falls below a threshold, or following defined succession or transfer events.
The precise mechanism is less important than the underlying principle:
The durability of control should bear some relationship to the durability of the circumstances that justified granting that control.
That recognizes something that is sometimes missing from the governance debate. Governance structures don't need to be static.
A structure appropriate for an entrepreneurial company at IPO may not be appropriate for a mature corporation 15 years later.
Put the Burden of Proof in the Right Place
I therefore think one-share-one-vote should remain the presumption rather than becoming an absolute rule.
When companies depart from it, the burden of proof should rise.
Investors should ask whether the founder has demonstrated exceptional value creation rather than simply possessing a compelling narrative. They should consider whether meaningful economic ownership accompanies voting control, whether the board can genuinely challenge management, whether minority shareholders are adequately protected and whether credible succession arrangements exist.
Most importantly, they should ask what causes the governance bargain to be reconsidered when the underlying facts change.
There is a significant difference between granting additional latitude to the founder of a proven enterprise and surrendering voting rights to the founder of a speculative business principally because markets are enthusiastic about its technology.
Exceptional Control Should Require Exceptional Justification
The governance community is right to be suspicious of concentrated power. History provides ample reason for that skepticism.
But sound governance principles shouldn't become substitutes for judgment.
One-share-one-vote should remain the default. Investors should nevertheless be capable of concluding that, under particular circumstances, accepting less voting influence can be economically rational.
The further a company moves away from proportional voting rights, however, the stronger the protections around duration, succession, economic alignment and minority shareholder interests should become. That is a more demanding standard than either automatically rejecting multi-class structures or accepting them because a founder happens to be successful.
The ultimate test of sound governance isn't simply whether power is widely dispersed. It is whether power is allocated wisely, constrained appropriately and capable of being reconsidered when the circumstances that justified it no longer exist.
Notes and References
1 Financial Conduct Authority. Policy Statement PS24/6, Primary Markets Effectiveness Review: Feedback to CP23/31 and final UK Listing Rules. June 2024. https://www.fca.org.uk/publication/policy/ps24-6.pdf